The Architecture of Money · Part 11
Why the World Still Needs the U.S. Dollar
About 57% of allocated reserves are still in dollars. A falling share is not disappearance.
This may be the most debated part of the series.
We often hear: “The dollar is losing its position.”
But if the dollar were really disappearing, why does it still appear everywhere?
In reserves. In trade. In bonds. In capital markets. In commodities. In international payments.
1. A Currency Is More Than a Banknote
An international currency works like a network.
If many people use it, the next person has an incentive to use it too.
This is the network effect.
It is similar to the internet. You do not use a social network only because its software is good. You use it because everyone else is there too.
The dollar has a similar advantage.
2. What the Reserve Data Say
According to the IMF’s COFER data, released March 27, 2026, the dollar accounted for 56.77 percent of allocated foreign-exchange reserves in the fourth quarter of 2025.
The euro was second at 20.25 percent. The Chinese renminbi was 1.95 percent.
The dollar’s share is lower than in some earlier periods.
But a declining share does not mean disappearance. Those are two very different ideas.
3. Why? Because of the Ecosystem
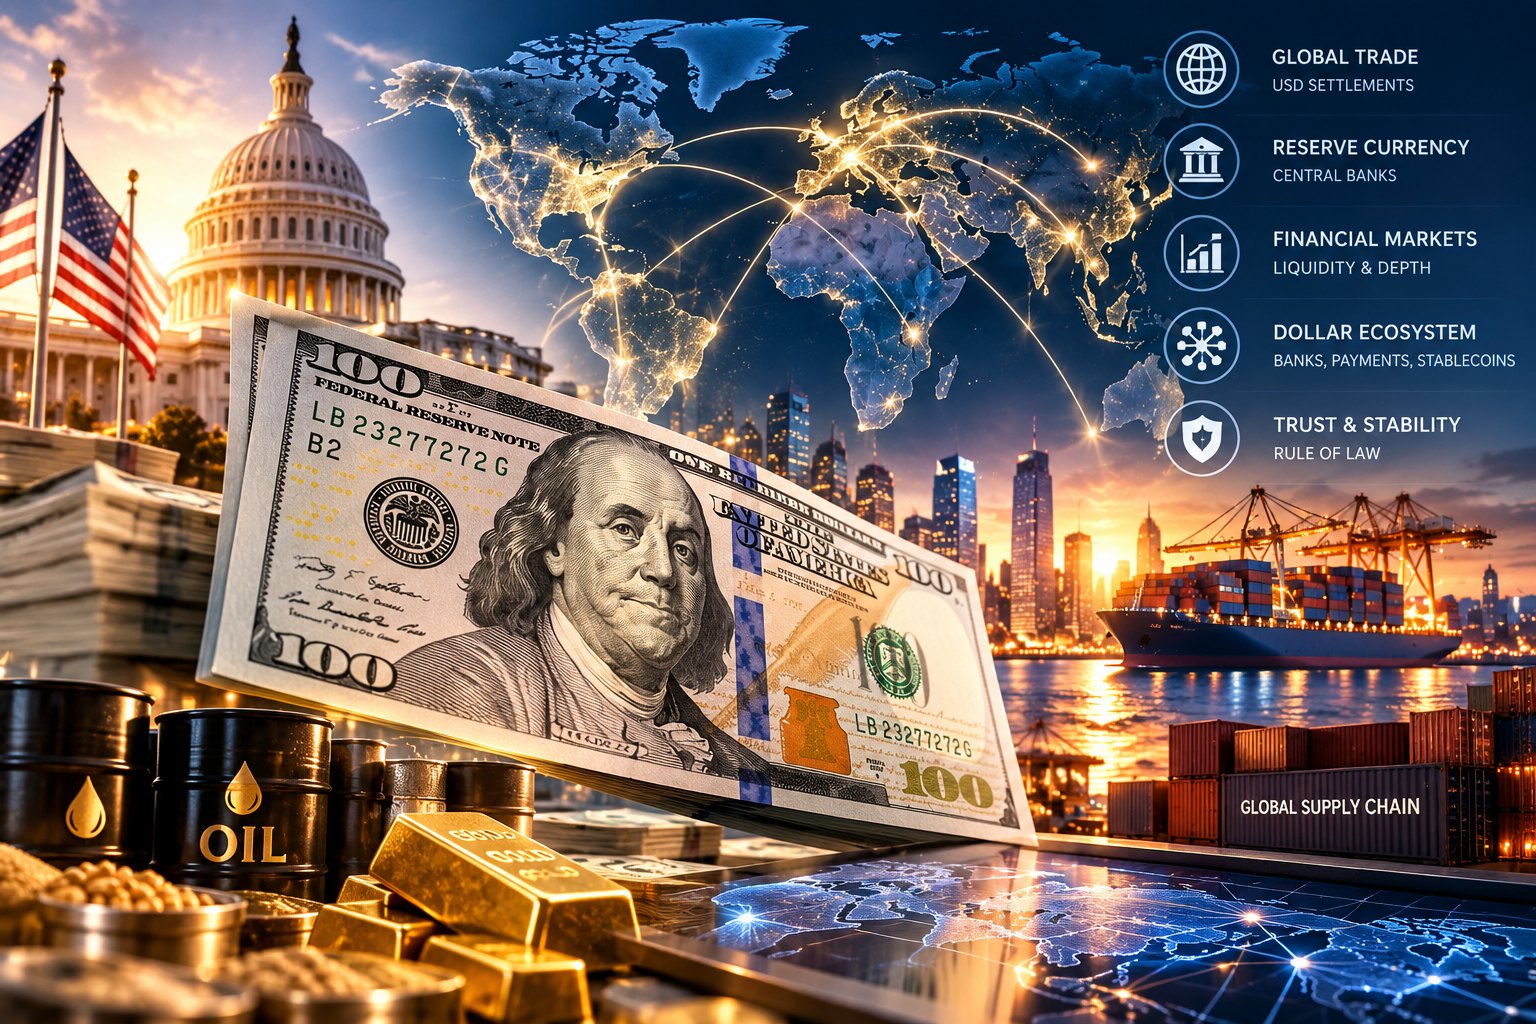
Behind the dollar sits an entire ecosystem:
- the U.S. Treasury market
- the banking system
- capital markets
- global trade invoicing
- payment infrastructure
- legal infrastructure
- institutional investors
- corporate finance.
To replace the dollar, you do not simply create a new currency. You have to build an entire new ecosystem.
4. My View
I do not think the world will use only one currency forever.
But I also do not think replacing the dollar is as simple as “BRICS creates a new currency, everyone abandons the dollar.”
The financial world does not work that way.
I think the future may look more like a multi-reserve system:
- the dollar remains large
- the euro remains important
- the renminbi may expand in certain areas
- gold remains a reserve asset
- digital assets may become a new layer.
5. The Interesting Part
If crypto grows while dollar stablecoins also grow, crypto may not weaken the dollar.
It may push the dollar deeper into the internet.
That is one of the most important hypotheses in this entire series.
6. The Real Battle
I do not think the future battle is simply dollar vs. gold, or dollar vs. BRICS.
Maybe the real battle is:
Who controls the infrastructure through which money moves?
If that question is right, we have reached the final part. Because money is no longer just money.
What This Means for Your Money
For most U.S. households, the reserve-currency debate matters less than one practical fact: your income, savings and debts are all in dollars, so your real risk is not “the end of the dollar” but inflation and interest rates eating into your budget.
Keep emergency savings where it is protected. The FDIC says deposit insurance “covers $250,000 per depositor, per FDIC-insured bank, for each account ownership category,” and you can confirm a bank is insured with the FDIC’s BankFind tool.
One step this week: check the APR on every balance you carry. When rates are high, paying down variable-rate debt is the most reliable move. Try our debt payoff calculator.
Sources: IMF Data Brief, Currency Composition of Official Foreign Exchange Reserves (COFER), 2025Q4 (Mar. 27, 2026); IMF, COFER dataset; FDIC, “Understanding Deposit Insurance”.
This is Part 11 of The Architecture of Money, a DebtRoute series on how money really works. Next: When Money Is No Longer Just Money. Follow DebtRoute on Facebook or join the DebtRoute Discord to get the next part. Educational content, not financial advice. Images are illustrative. DebtRoute is not affiliated with the IMF or the U.S. Treasury.